

What does each path actually put in your pocket?
The sale price isn’t what you keep. What you keep is the net: the price minus everything it costs to get there. Take one $300,000 Twin Cities house and sell it two ways: to us for cash, or through a listing with Ryan on NorthstarMLS. If the two nets are close, speed and certainty might decide it. If they’re far apart, the math decides it. Cash and listing are two of our four paths.
The example house
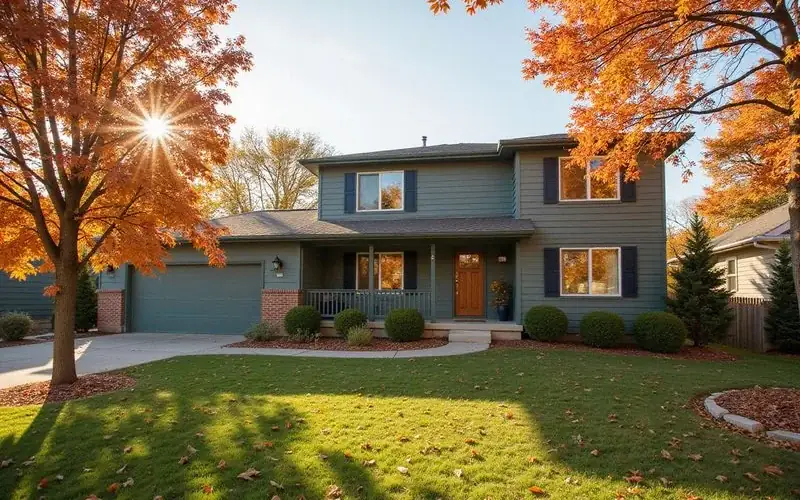
A 1978 split level in Burnsville. Three bedrooms, two baths, original kitchen, a furnace that’s 17 years old, and a roof with a few years left. Going by recent sales of similar houses nearby, it would sell for around $300,000 in its current shape with light prep. The owner has 60 to 90 days to work with.
The two net sheets, side by side
Scroll to compare
| Line item | Listing with Ryan | Cash sale to us |
|---|---|---|
| Sale price | $300,000 | $235,000 |
| Commission (5.5% example) | -$16,500 | $0 |
| Deed tax, title and closing fees (about 1.5%) | -$4,500 | $0, we pay them |
| Prep and repairs before listing | -$8,000 | $0 |
| Holding costs (3 months at $1,800) | -$5,400 | -$900 (about 2 weeks) |
| Moving help | $0 | +$1,000 |
| Net before mortgage payoff | $265,600 | $235,100 |
| Days to cash | About 90 | 7 to 14 |
In this example, listing nets about $30,000 more. That’s a lot of money, and for most sellers in this spot, listing is the right call. Ryan would say so.
What the table doesn’t show
Listing comes with risks that never show up on a net sheet. The buyer’s inspection can reopen the price, the appraisal can come in low, or the loan can fall through a week before closing. A cash sale to us skips those three. Is that certainty worth the difference? That’s your call.
What changes the answer
The gap moves fast when the house or the timeline changes.
More repairs. Say the same house needed a $25,000 roof and a $12,000 furnace before a buyer’s lender would sign off. Your prep costs jump, and the sale price may still drop. The gap can shrink to a few thousand dollars.
Less time. Have to close in three weeks? Then listing isn’t really an option. It’s cash vs. a price cut to find a fast buyer.
Higher holding costs. A vacant house in winter with a mortgage, utilities and insurance can cost $2,500 or more a month. Every extra month eats the listing advantage.
A buyer who falls through. Losing a buyer after 30 days under contract resets the clock. Two more months at $1,800 costs $3,600. And that’s before you count the stress.
Minnesota costs to know about
- State deed tax: about 0.33% of the sale price, typically paid by the seller. Hennepin and Ramsey counties add a small environmental fee on top.
- City inspections before a sale: Minneapolis and St. Paul both make sellers pay up front for a Truth in Sale of Housing evaluation. Minneapolis can flag repairs you have to make. St. Paul’s report is disclosure only.
- Radon, well and septic disclosures: separate from the main seller disclosure. They don’t cost anything, but they’re one more step.
- Title insurance and closing fee: split between buyer and seller depending on the contract.
For every fee in detail, see the cost to sell a house in Minnesota.
When each path wins
| Listing usually wins when | Cash usually wins when |
|---|---|
| The house is in decent shape | Repairs are big enough to block a buyer’s loan |
| You have 60+ days | You have a deadline under 30 days |
| You can handle showings | The house is full of stuff, has tenants, or sits empty in winter |
| Title is clean | Liens, probate gaps or a foreclosure are involved |
How to run your own numbers
Plug in your own list price estimate, commission, repair list and monthly costs. Our free cash vs. list net sheet calculator does the math. Or ask Ryan. He’ll walk you through what the house could list for, what you’d net by listing it, and our cash offer. Then he’ll tell you straight which one comes out ahead. You can list with Ryan or sell for cash, and you’ll know exactly what you gave up either way.
This guide is general information, not legal, tax or financial advice. For your own situation, talk to a Minnesota attorney or tax professional.